Why Bigger Isn't Always Better
Modern life loves the idea that “more” equals “better.” Bigger homes, bigger cars, bigger shopping centres, bigger everything. Business culture has absorbed the same logic: chase scale, chase market share, chase growth. If you’re not getting bigger, the assumption is that you’re falling behind.
But the real world keeps reminding us that size comes with strings attached and often, those strings get tangled.
Large organisations tend to accumulate bureaucracy the way old houses accumulate dust. Decision-making slows. Innovation stalls. Reacting to change becomes a multi-step process involving committees, subcommittees, and someone who’s been “looped in” but never replies.
Meanwhile, smaller players slip into the market with agility, creativity, and the ability to “turn on a dime”. They don’t need to “seek alignment”; they just get things done.
A few everyday examples:
- Service quality drops as size increases. Boutique hotels still outperform big chains on warmth, care, and attention.
- Local knowledge disappears. The neighbourhood hardware store owner who knew your name gets replaced by a very polite senior citizen pointing you toward aisle 67B.
- Innovation slows. Big companies often can’t move fast enough to become the next Apple or Canva — but small teams can.
Scale can be powerful, but it can also be clumsy.
For years, the Australian superannuation industry has promoted the idea that larger funds deliver better outcomes because they spread fixed costs across more members. But research has repeatedly challenged this assumption.
- A fairly recent working paper for APRA found no consistent link between fund size and performance.
- Indeed, the analysis showed that some tiny funds were just as efficient as the largest ones – and in some cases, more so.
The $4.1 trillion Australian super landscape has slowly continued to consolidate, but the core insight remains scale alone doesn’t guarantee efficiency. Culture, governance, investment discipline, and member focus matter far more than raw size.
The Global Financial Crisis taught us that breaking up big banks doesn’t magically remove systemic risk. Whether a bank is large or small, the financial system is a web and when one strand snaps, the tension travels.
Spain’s experience during the GFC is a perfect example: it wasn’t just the big banks that caused trouble. A cluster of small savings banks created just as much disruption collectively as a single large failure.
The lesson: risk isn’t only about size – it’s about interconnectedness.
Arguments about scale often get stuck in spreadsheets and economic models. But the real test – “the pudding” – is what people actually experience.
And the pudding keeps telling the same story:
- The café that remembers your order beats the chain that gives you a loyalty card.
- The small accounting firm that answers your call beats the giant one that sends you to a portal.
- The local mechanic who knows your car beats the dealership that treats you like a ticket number.
People don’t crave “scale.” They crave competence, care, and connection – things that are easier to deliver when you’re not managing an empire.
Small and medium-sized enterprises remain the backbone of Australia’s economy. Today, SMEs employ around two-thirds of the private-sector workforce, and the pattern is similar across OECD countries.
They innovate, adapt, serve communities, and increasingly, they combine local presence
with global reach through digital tools.
Big business may dominate headlines, but small business drives the heartbeat of the economy – and every big business started as a small one.
Size isn’t inherently good or bad. It’s simply a tool – and like any tool, it works brilliantly in some situations and terribly in others.
But when it comes to service, innovation, responsiveness, and human connection, small often has the edge. And in a world obsessed with scale, that’s worth remembering.
All food for thought
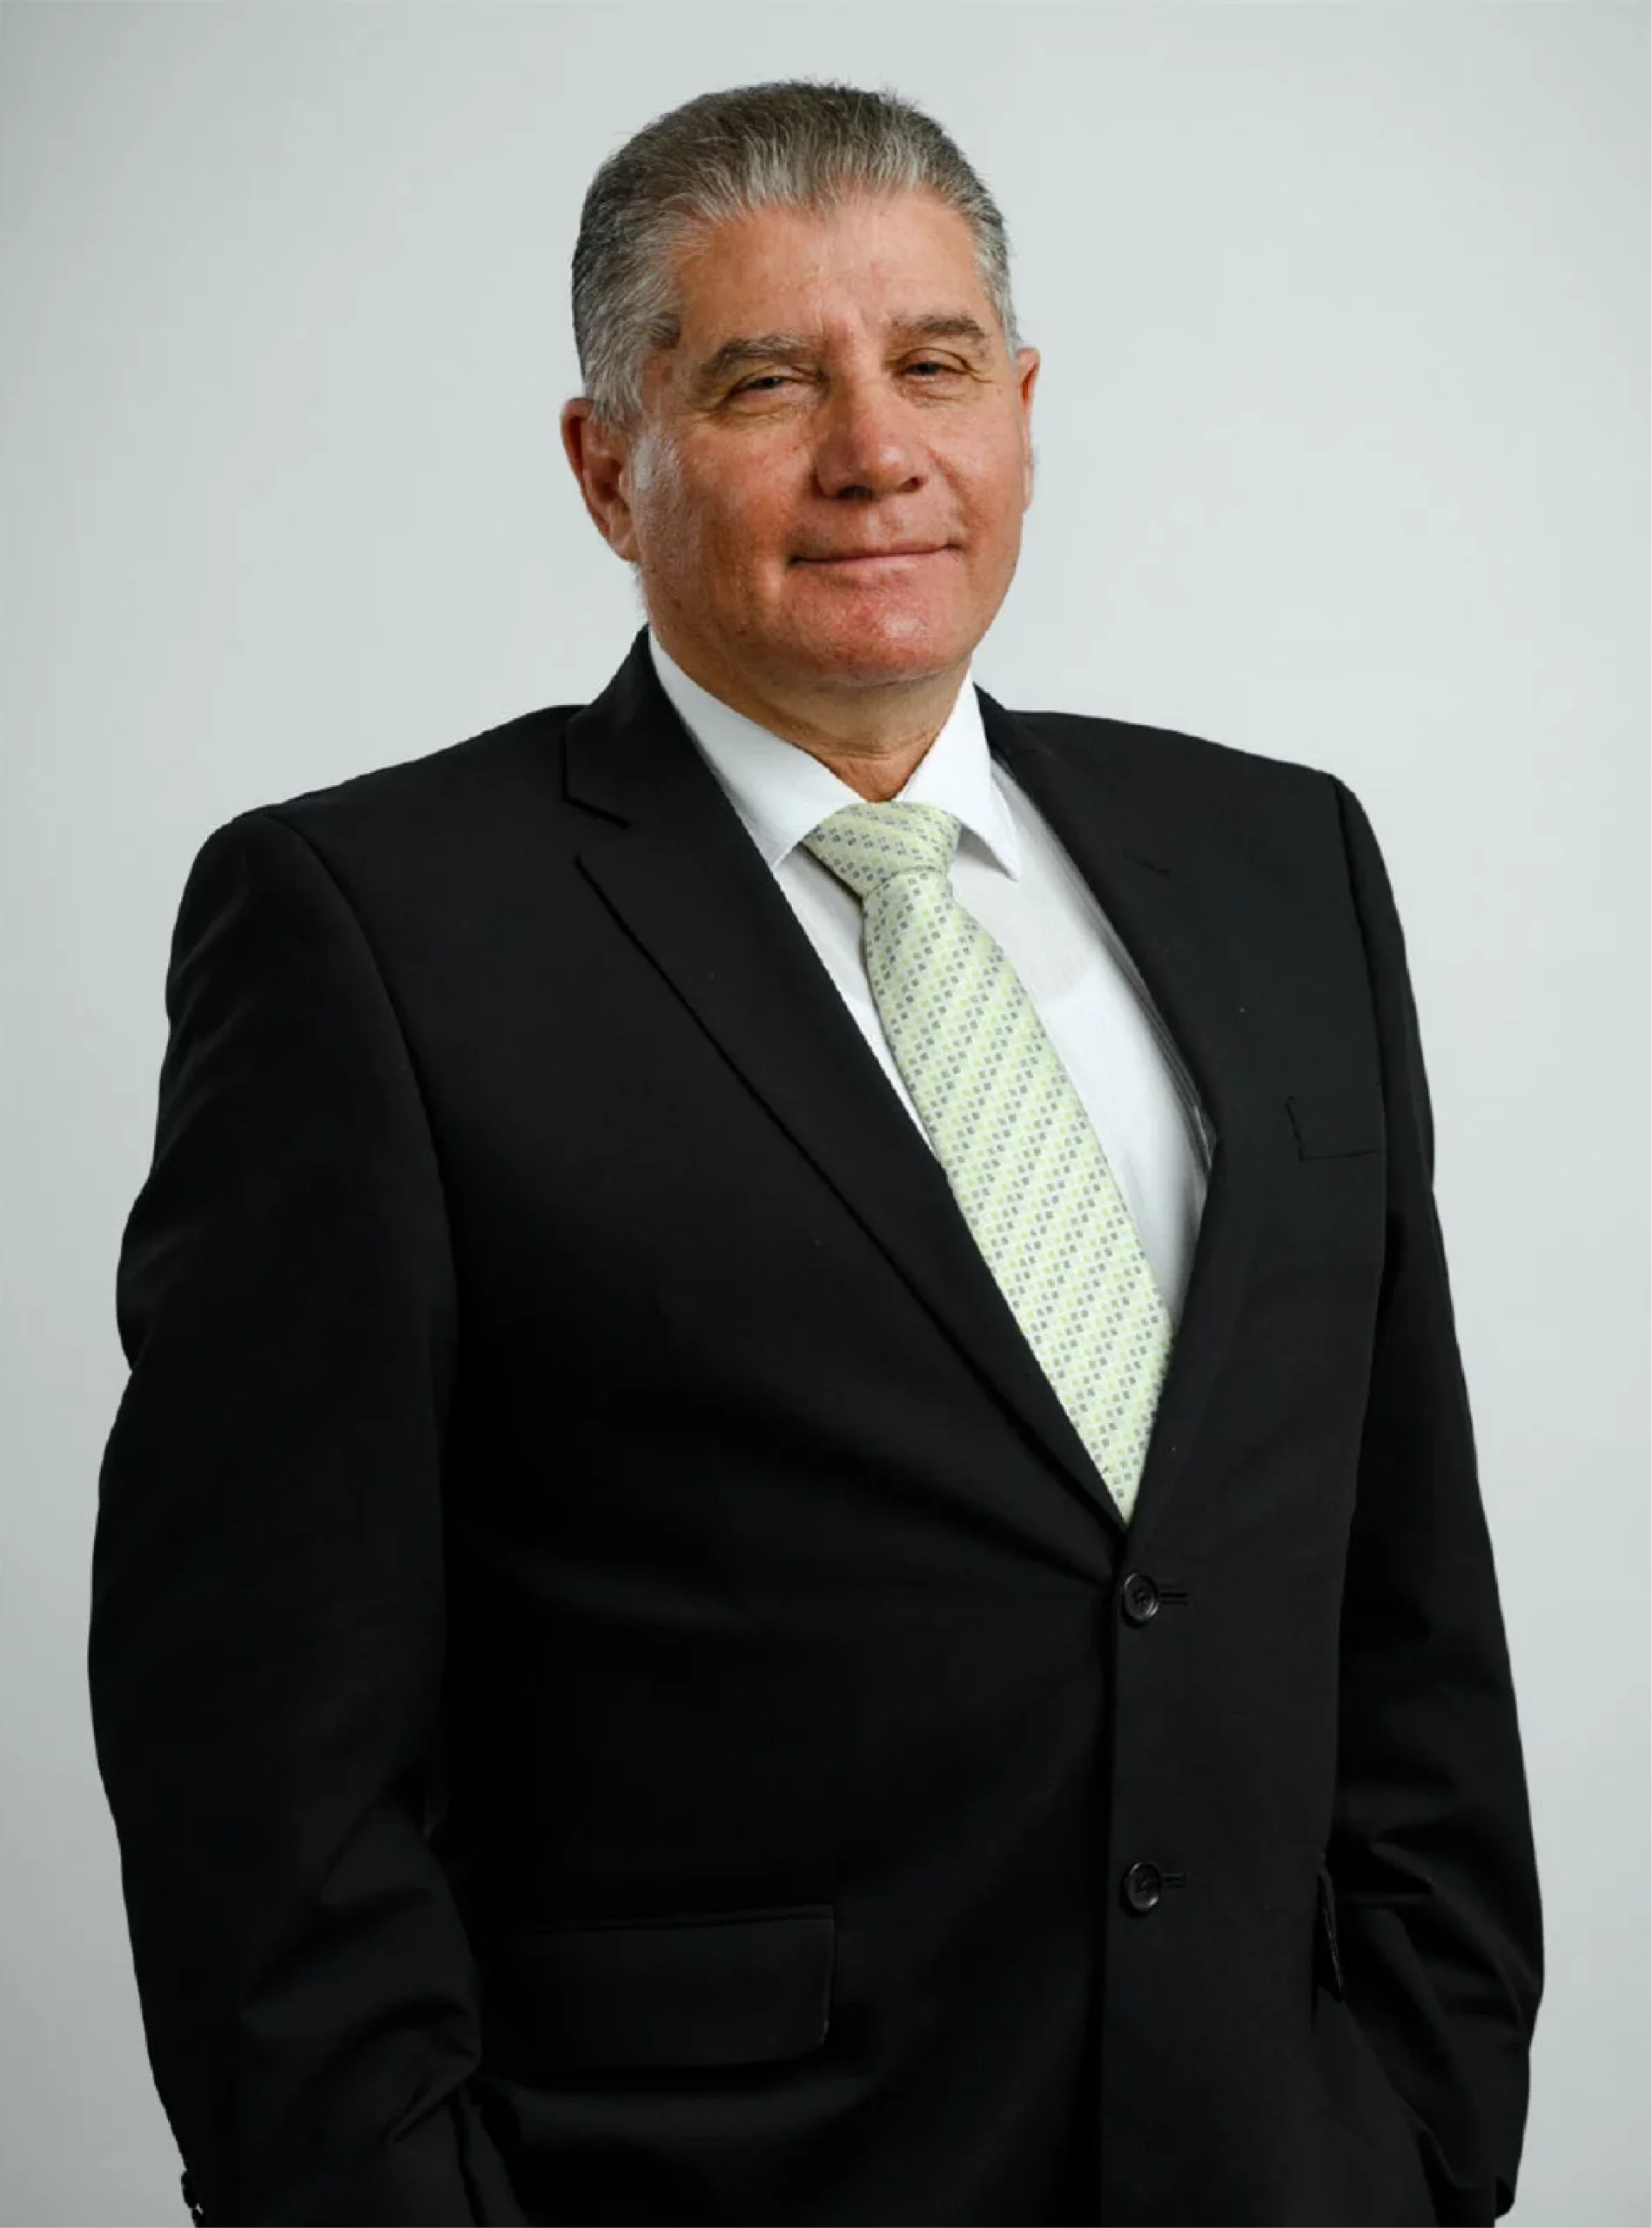
John (JT) Thomas, OAM KSS
Independent Chairman
This opinion piece is provided by John (JT) Thomas, a 50- year veteran of the financial services industry and since 1987 a specialist in commercial mortgage funds. Considered by many to be the father of the modern commercial mortgage fund sector, JT helped establish and then managed – for 17 years – what became the largest and most successful commercial mortgage fund in Australia – The Howard Mortgage Trust – with assets exceeding $3 billion. Under JT’s stewardship, investors never lost one cent of their investments and indeed, investors always received competitive monthly returns. JT was also Chair of the $40 billion mortgage trust industry sector working group.
JT has been proudly involved with Princeton for 13 years and Chairs both the Princeton Credit Committee and the Princeton Compliance Committee. Since October 2025 he has been the Independent Chair of the Princeton Board.